30 Days Late on Mortgage? What Really Changes at 30, 60, and 90 Days in NC
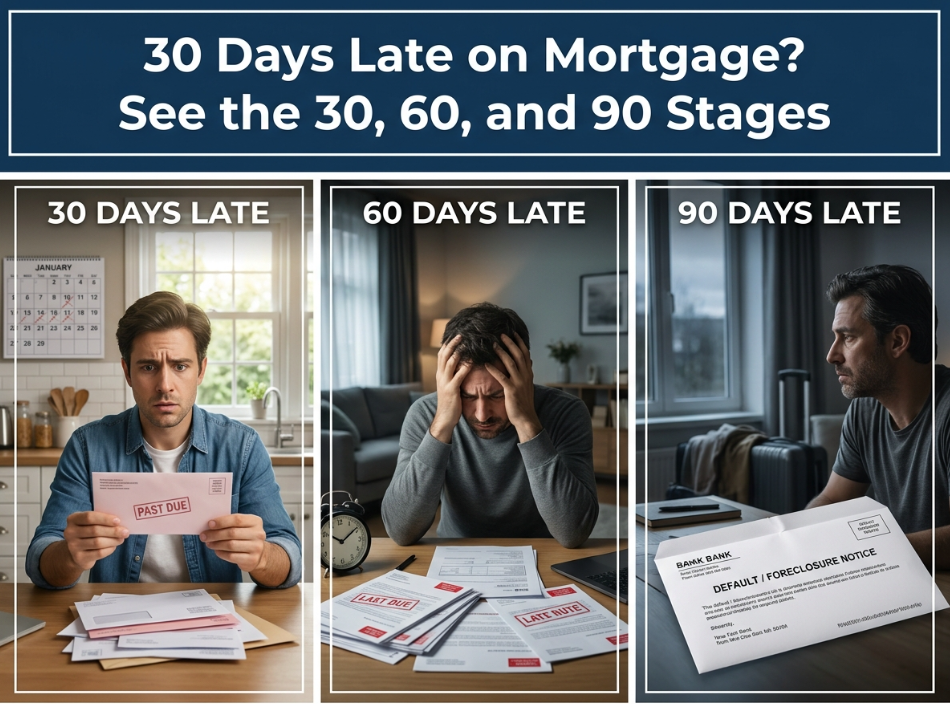
If you are 30 days late on your mortgage, you are not automatically in foreclosure. You are, however, past the point where one missed payment feels temporary.
What matters now is whether one missed payment becomes two, then three. The longer that continues, the harder the problem becomes to fix without pressure.
Before 30 Days, Deal With the Payment You Actually Missed
A mortgage can be late for several days without being 30 days delinquent. Your loan may also give you a short grace period before fees appear.
If payday is close, call the servicer and ask what amount makes the account current today. Do not assume your normal monthly payment is enough.
Before the month rolls over, find out:
- The exact amount currently due
- Whether a late fee was added
- When the grace period ends
- Whether another payment is about to come due
- Whether a returned payment changed the balance
- Whether escrow or insurance changed the normal payment
What Happens If You Are 30 Days Late on Mortgage?
At 30 days late on a mortgage, the servicer may report the delinquency to the credit bureaus. That can affect credit even though foreclosure has not started.
Federal rules also require many servicers to begin early contact and send information about possible loss mitigation help. The CFPB explains those servicing duties clearly.
Ask the servicer:
- What amount brings me completely current?
- Has the late payment been reported?
- What hardship options are available?
- What documents do you need?
- Is another payment already due?
- When will the next late fee be added?
Sixty Days Late Is Where the Math Gets Harder
At 60 days late on a mortgage, two regular payments may now be unpaid. The arrears can grow much faster than most household budgets can absorb.
Suppose your payment is $1,850. Two missed payments equal $3,700 before late charges, while another $1,850 payment may already be getting close.
Put the household numbers on paper:
- Take-home income
- Normal mortgage payment
- Food and utilities
- Transportation and insurance
- Childcare or medical costs
- Other secured debts
- Money actually left for arrears
- Savings you can use without emptying your emergency fund
If the numbers do not work: promising more than the budget can carry only creates another missed payment. Review the earlier foreclosure-prevention options instead.
Can You Catch Up After Two Missed Payments?
Yes, sometimes. A short job interruption may end, overtime may return, or another temporary expense may disappear. The important question is what happens financially afterward.
Spreading $3,700 over six months adds about $617 monthly. If your regular mortgage is already tight, that extra amount may make the arrangement unrealistic.
A catch-up plan should still leave room for:
- The next regular mortgage payment
- Food and household utilities
- Transportation
- Insurance
- Childcare
- Minimum debt payments
- A small emergency cushion
Ninety Days Late Requires a Bigger Decision
At 90 days late on your mortgage, you may be three full payments behind. The question now is whether the mortgage still fits your household income.
A short job gap can end. A permanent pay cut, divorce, or new caregiving expense may not. Those situations need very different financial answers.
By this stage, get these figures in writing:
- Total arrears
- Current reinstatement amount
- Full mortgage payoff
- Status of any assistance application
- Missing documents
- Whether the loan has been referred for foreclosure
- Any known legal deadline
- The name or department handling your loss-mitigation file
Keep this distinction clear: being 90 days late on your mortgage does not automatically mean a North Carolina foreclosure has started, but the federal 120-day threshold is close.
The Timeline Is Easier to Understand This Way
The numbers matter, but the real change is what you need to decide at each stage. Thinking that way makes the timeline much more useful.
| Stage | What is changing | The useful question |
| Under 30 days | Late fees and another due date | Can I become current before the next payment? |
| 30 days | Credit reporting becomes possible | Can I stop one missed payment becoming two? |
| 60 days | Arrears are harder to absorb | Can my budget support a catch-up plan? |
| 90 days | Formal foreclosure risk is closer | Is this mortgage still affordable long term? |
| 120+ days | A foreclosure filing may become possible | What deadlines and formal options apply now? |
This is not a guaranteed schedule for every loan. Servicer procedures, assistance applications, investor rules, and loan terms can change the exact path for you.
What Changes Around 120 Days in North Carolina?
Federal rules generally prevent the first foreclosure notice or filing until a borrower is more than 120 days delinquent, although limited exceptions can still apply.
North Carolina also requires a pre-foreclosure notice for many primary-residence loans. The state law generally requires that notice at least 45 days before filing begins.
If that notice arrives, compare it with your records:
- Last payment credited
- Past-due amount
- Added fees
- Servicer contact details
- Assistance information
- Date shown on the notice
- Any figure that does not match your statements
Do not ignore a mismatch: an incorrect payment date or unexpected charge is easier to investigate before the hearing stage than after legal deadlines begin moving.
Catching Up Is Not Enough if the Mortgage Still Does Not Fit
A homeowner can clear the arrears and still have an unaffordable mortgage. That is why the reinstatement amount should never be the only number considered.
Imagine borrowing $6,000 from family, becoming current, then facing the same monthly shortage thirty days later. The account improved, but the household problem did not.
Look six months ahead and include:
- Regular mortgage payment
- Taxes and insurance
- Utilities
- Food and transportation
- Childcare
- Other debts
- Normal home repairs
- Income you genuinely expect to receive
- Any income that may end or change soon
The honest test: if those numbers still leave a monthly shortfall, catching up may only postpone the same problem rather than solve it.
When a Backup Property Plan Becomes Worth Considering
One missed payment is not a reason to rush into selling. A temporary setback may resolve once income returns and the normal mortgage becomes manageable again.
A backup plan becomes more useful when arrears keep growing, assistance does not solve the payment issue, or the house no longer fits the household budget.
Before considering a sale, find:
- Current mortgage payoff
- Second mortgage or HELOC balance
- Tax or HOA liens
- Realistic property value
- Likely selling costs
- Available equity
- Time needed to close
Where FixItMoney fits:
- Property review: We can look at arrears, payoff, equity, condition, and available time for North Carolina homeowners.
- Possible route: If keeping the mortgage no longer works, an as-is home sale or another property-based option may be worth comparing.
- Important limit: FixItMoney is not a mortgage servicer or law firm, so loan assistance and legal questions still belong with the appropriate professional.
Start With the Next Payment, Not the Worst-Case Scenario
If you are 30 days late on your mortgage, start with the amount due today, why the payment was missed, and whether next month’s mortgage is affordable.
At 60 days, test the catch-up plan against your real budget. At 90 days, decide whether you are fixing a temporary setback or carrying an unaffordable loan.
Three answers matter most:
- What amount makes the loan current today?
- Can the household afford the regular payment in the future?
- What happens if another payment comes due before you catch up?
- If the account keeps slipping, review the later North Carolina foreclosure deadlines before legal deadlines control more of the decision.